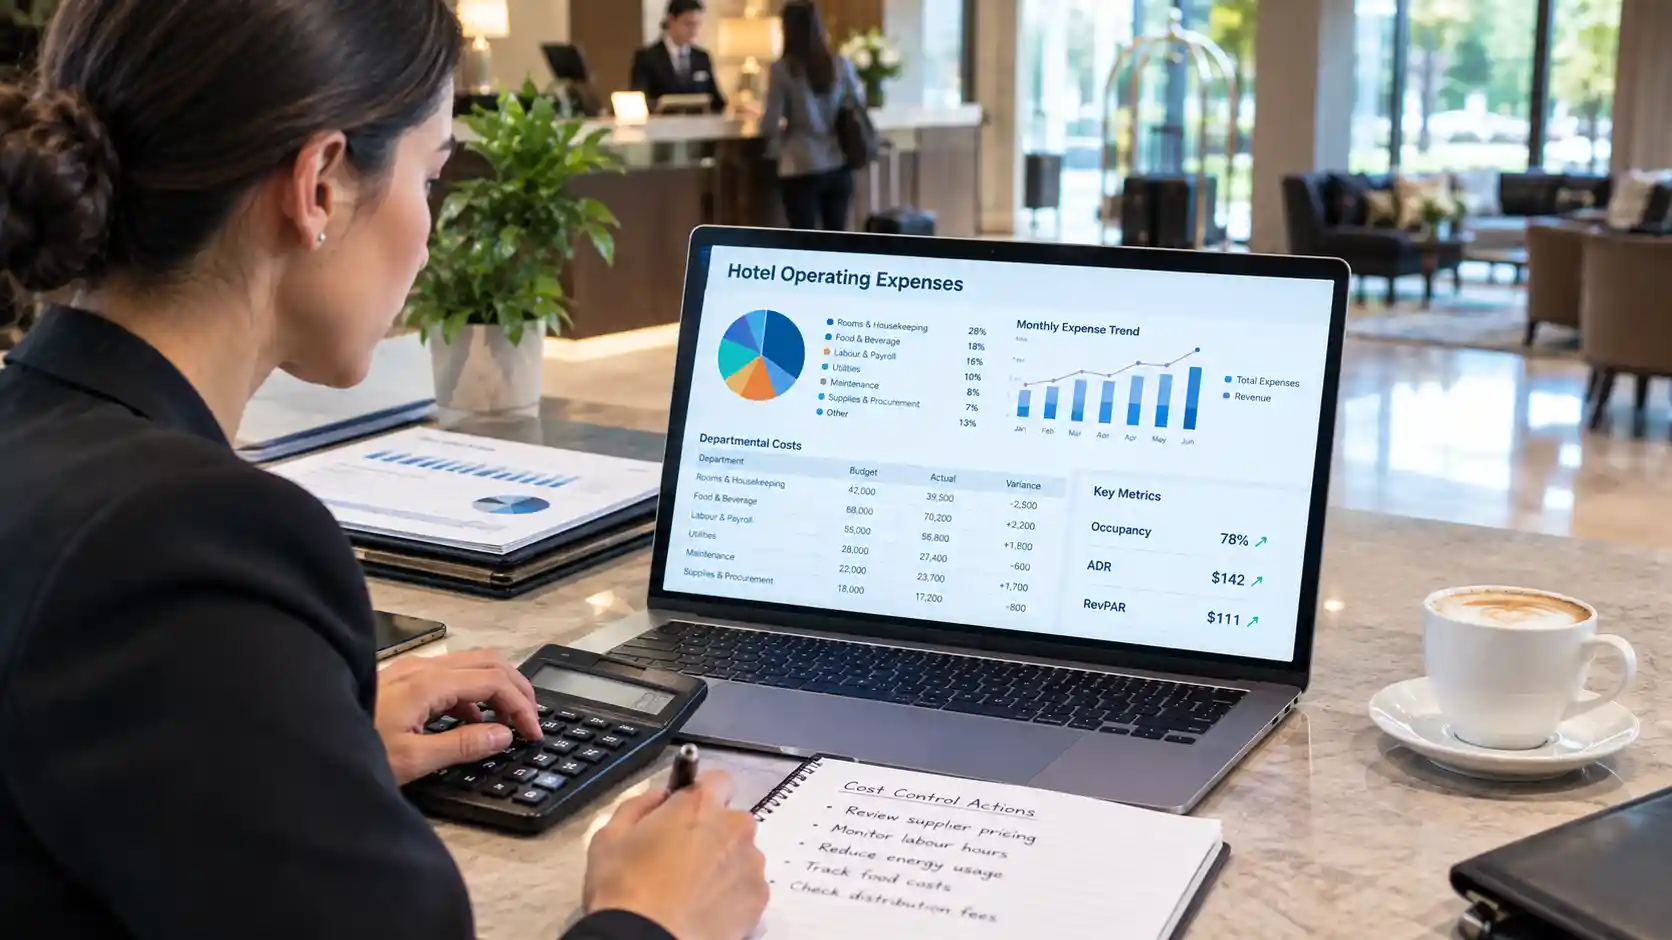
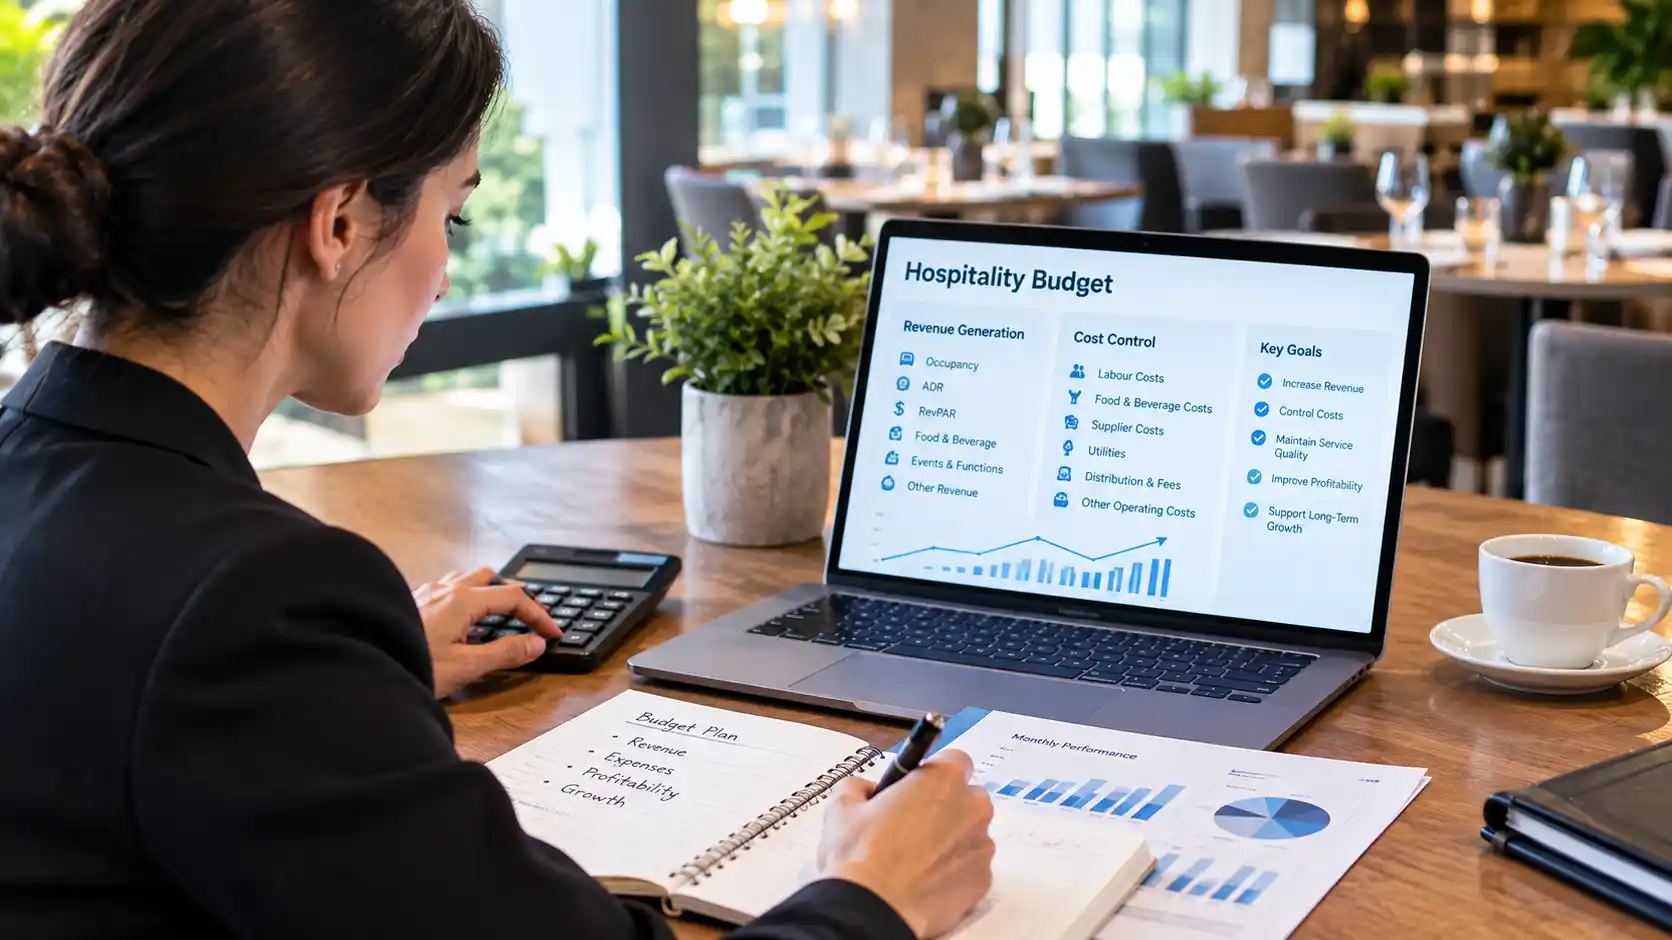
Hospitality budgeting is not simply about reducing expenses or finding ways to increase sales. A sustainable budget needs to connect both sides of the business: how much revenue the operation can realistically generate and how much it needs to spend to deliver that revenue.
For a hotel, restaurant or other hospitality business, this means looking at occupancy, room rates, labour, food and beverage costs, supplier spending, distribution fees, utilities and other operating expenses together. A decision that lowers one cost can sometimes affect service quality or revenue, while an initiative that increases sales may also introduce additional labour, commission or operating costs.
The goal is therefore not to minimise every expense or maximise every possible sale. It is to make informed decisions that improve profitability while maintaining appropriate service standards and protecting long-term demand.
Why Cost Control and Revenue Generation Need to Work Together
Cost control and revenue generation are closely connected. Increasing revenue does not necessarily improve profitability if the additional sales require disproportionately higher costs. Likewise, reducing costs can weaken the operation if the savings result in service delays, maintenance problems, poor food quality or other issues that affect guests.
A useful budgeting process considers three questions for major financial decisions:
- What will happen to revenue?
- What will happen to operating costs?
- What effect could the decision have on service quality and future demand?
This approach helps managers assess the commercial effect of a decision rather than looking at one expense or revenue figure in isolation.
For example, reducing labour hours may lower payroll in the short term. However, if the change increases waiting times, housekeeping delays or guest complaints, the immediate saving may come with an operational cost. Similarly, increasing room rates may raise average daily rate (ADR), but managers also need to monitor occupancy and RevPAR to understand the broader effect on room revenue.
Build the Hospitality Budget Around Real Operating Drivers
A useful hospitality budget starts with realistic operating assumptions. Instead of setting a single annual revenue target, managers can build the forecast around factors that directly influence performance.
For accommodation businesses, these may include expected occupancy, ADR, RevPAR, room availability and seasonal demand. Restaurants may need to consider covers, average spend per customer, food costs, labour and trading patterns. Other hospitality operations may have different revenue and cost drivers.
The budget should then be reviewed against actual results. Comparing budget versus actual performance helps identify where assumptions were inaccurate and where costs or revenue have moved unexpectedly.
Variance analysis is particularly useful. A variance does not automatically mean that the business is performing badly. Revenue may be below budget because demand changed, while a cost variance may result from higher supplier prices or additional staffing requirements. The important question is why the variance occurred and whether management needs to respond.
A rolling forecast can also help businesses update their expectations as new information becomes available. This is particularly relevant in hospitality, where seasonality, events, booking patterns and changing demand can affect financial performance.
For businesses wanting to strengthen their budgeting process, resources such as building a flexible hospitality budget and budgeting tips for hospitality businesses provide useful related areas to consider.
Control Costs Without Undermining Operations
Effective cost control is about understanding what the business is paying for and whether each expense supports the operation.
Labour is a major consideration for many hospitality businesses. Rather than simply reducing staffing, managers can compare labour hours with occupancy, covers, service demand and productivity. Scheduling should reflect expected demand while allowing enough capacity to maintain required service standards.
Procurement is another important area. Regularly reviewing supplier pricing, purchasing patterns, stock levels and waste can identify opportunities to control spending. Food and beverage businesses can monitor food costs alongside sales and menu performance rather than looking at purchasing costs alone.
Outsourcing can also be considered, but it should not automatically be treated as a cost-saving solution. Before moving a function outside the business, compare the total in-house cost with the proposed supplier cost, contract terms, management time, service requirements and expected volume.
Energy and other property-related expenses also deserve regular attention. Managers can track consumption, identify unusual increases and assess whether operational changes or efficiency measures are financially worthwhile.
The key is to measure the effect of cost-control decisions rather than assuming that a lower expense is always a better outcome.
Use Revenue Management to Improve Financial Performance
Revenue generation should also be managed with the cost base in mind.
For hotels, dynamic pricing allows room rates to respond to changes in demand, booking pace, seasonality, events and market conditions. However, increasing the room rate does not automatically produce a better financial result. Managers should consider ADR alongside occupancy and RevPAR and review how pricing decisions affect booking behaviour.
Revenue management can also involve distribution. Online travel agencies can provide access to customers, but the associated commission and distribution costs need to be included when assessing the value of different booking channels. Comparing direct and third-party bookings can provide a clearer view of the revenue contribution from each channel.
Businesses can also review ancillary revenue opportunities. These might include food and beverage, parking, upgrades, events, activities or other services relevant to the property. Before introducing a new revenue stream, calculate the expected incremental revenue against additional labour, supplies, commissions, transaction costs and operational capacity.
For further reading, see hotel revenue and yield management, hotel revenue strategies and how hotels use revenue models to maximise earnings.
Protect Guest Experience While Managing the Budget
Cost control should have clear operational boundaries. A saving that reduces service quality may create problems that are more expensive to address later.
Managers can monitor indicators such as guest complaints, review trends, response times, service delays, repeat bookings and labour productivity alongside financial measures. These indicators help show whether a cost decision is affecting the guest experience.
The same principle applies to revenue initiatives. Higher prices, additional fees or new packages need to provide appropriate value and fit the expectations of the target market.
Guest experience should therefore be treated as part of the financial decision-making process rather than as a separate issue from budgeting.
Use the Right Financial and Operational Data
Technology can make budgeting and performance management more practical, but different systems serve different purposes.
A property management system (PMS) can provide operational and guest information, while a revenue management system (RMS) can support pricing and demand analysis. Accounting systems help track income, expenses, assets and financial reporting, while energy-management systems focus on monitoring and controlling resource consumption.
The important consideration is not simply whether a business uses technology. Managers should assess whether the systems provide useful data, integrate with existing operations, support reporting and reduce unnecessary manual work.
Financial information also needs to reach decision-makers in time to be useful. Timely financial updates for hospitality businesses and automating financial management in hospitality are relevant to this part of the process.
Monitor the Metrics That Connect Revenue and Costs
A practical hospitality budgeting process should focus on measures that explain what is happening financially and operationally.
For hotels, useful measures can include:
- Occupancy: Shows how much available room capacity is being sold.
- ADR: Shows the average room rate achieved.
- RevPAR: Connects room revenue with available room capacity.
- Labour cost: Helps managers understand staffing costs relative to operational activity.
- Departmental performance: Shows which areas are generating revenue and which are consuming resources.
- Budget versus actual: Highlights financial variances that require investigation.
These measures become more useful when reviewed together. For example, an increase in ADR alongside a significant occupancy decline should be investigated rather than judged from the rate increase alone.
Businesses can also use hospitality analytics and historical data to forecast hospitality revenue to improve the quality of future budgeting and forecasting decisions.
Review the Budget Regularly and Adjust When Conditions Change
An annual budget should provide direction, but it should not prevent managers from responding to changing conditions.
Regular financial reviews allow businesses to compare actual revenue and expenses with the original assumptions. Where significant variances occur, managers can determine whether the change is temporary, seasonal or likely to continue.
This can lead to practical adjustments such as changing staffing levels, reviewing purchasing, updating revenue forecasts, reassessing distribution channels or modifying pricing assumptions.
The objective is not to change the budget every time performance moves slightly. It is to identify meaningful changes early enough to make informed operational decisions.
Conclusion
Balancing cost control and revenue generation in hospitality requires more than cutting expenses or increasing prices. The strongest budgeting decisions consider revenue potential, operating costs and guest experience at the same time.
Managers can strengthen this process by building budgets around realistic operating drivers, comparing budgeted and actual results, investigating variances, monitoring labour and procurement costs, reviewing distribution expenses and using revenue management measures such as occupancy, ADR and RevPAR.
The aim is not to minimise every cost or pursue every available revenue opportunity. It is to understand the financial and operational consequences of each decision and allocate resources where they support profitable, sustainable operations.
For businesses that need broader financial support, hospitality accounting and financial services can provide a useful starting point for reviewing budgeting, reporting and financial management needs.
FAQ
What is the main goal of hospitality budgeting?
The main goal is to plan and monitor revenue and expenses so the business can allocate resources effectively, manage financial risks and make informed operating decisions. A useful hospitality budget should reflect the factors that actually drive revenue and costs.
How can hotels control costs without affecting guest experience?
Hotels can monitor labour productivity, procurement, energy use, waste and other operating expenses while also tracking service indicators. Cost reductions should be assessed against their potential effect on service quality, guest complaints, delays and operational performance.
Why are occupancy, ADR and RevPAR important?
These measures provide different views of hotel room performance. Occupancy shows the proportion of available rooms sold, ADR shows the average room rate achieved, and RevPAR connects room revenue with available room capacity. Reviewing them together gives managers a more useful picture than relying on one metric.
How often should a hospitality budget be reviewed?
The frequency depends on the size and operating model of the business, but regular reviews are important. Comparing actual results with the budget and investigating significant variances allows managers to respond when revenue, costs or operating conditions change.
How can hospitality businesses improve revenue without simply increasing prices?
Businesses can review pricing, distribution channels, ancillary services, packages and other relevant revenue opportunities. Each option should be assessed against its additional costs, labour requirements, commissions, transaction fees and operational capacity before it is introduced.