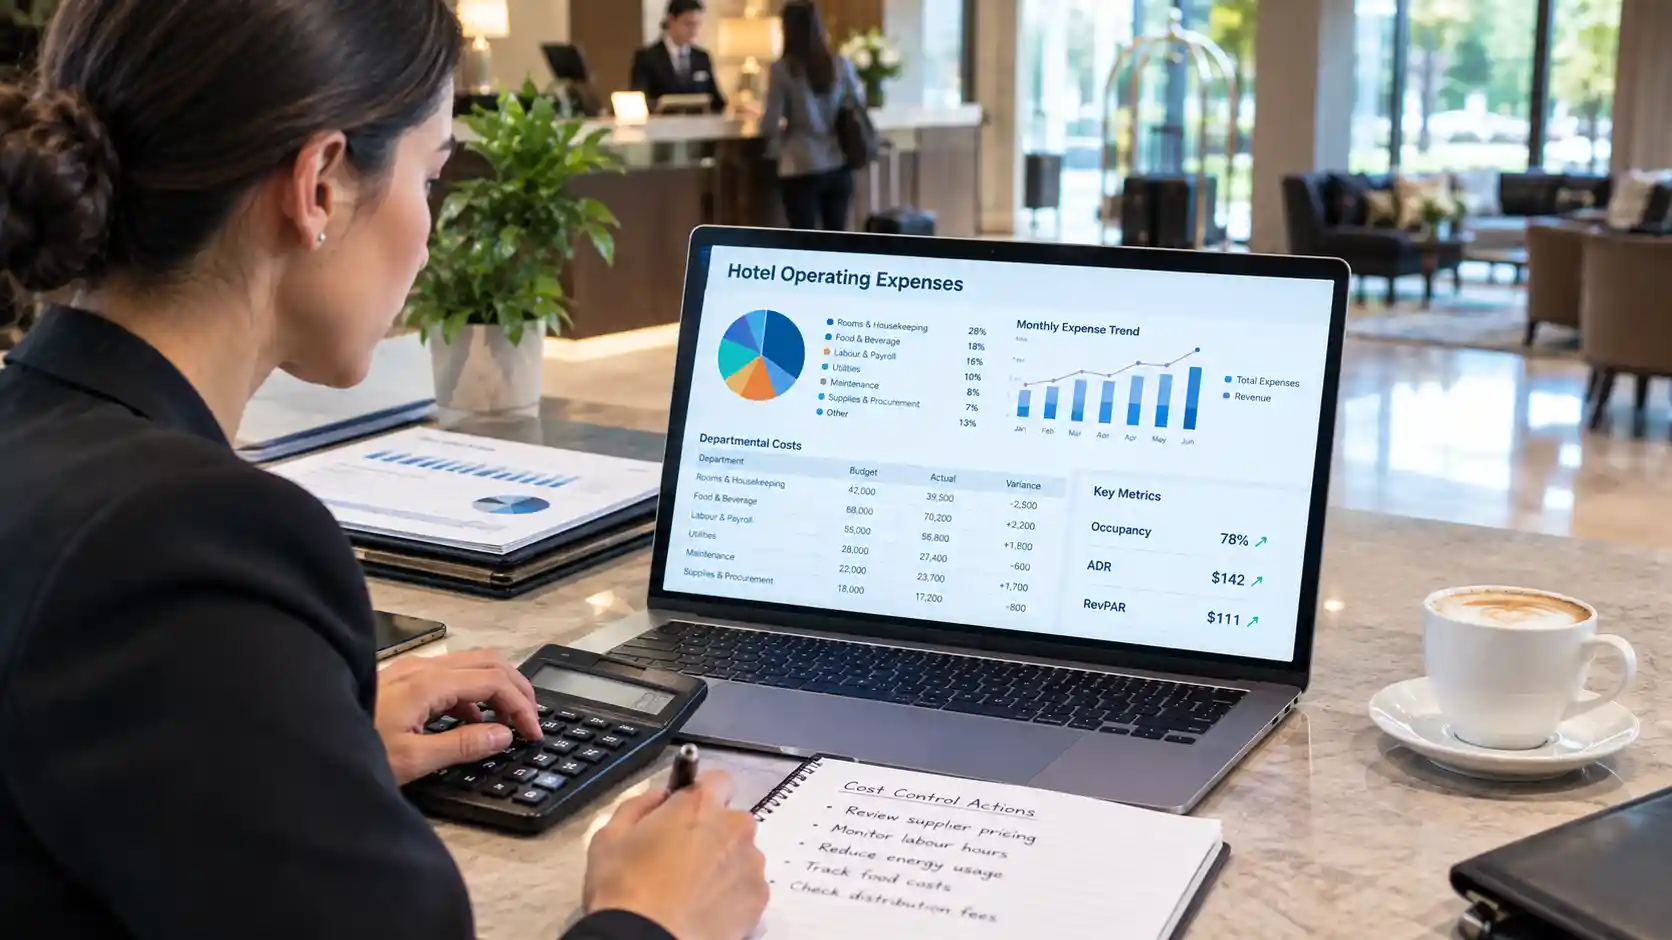
Running a hotel means making financial decisions while the numbers are still moving. Rooms are being sold, cancellations are coming in, restaurant revenue is changing throughout the day, labour costs are accumulating and distribution fees can affect the value of each booking.
That is why hotel managers need more than a month-end profit and loss statement. A small set of financial and operating metrics can provide an early view of how the property is performing and where attention may be needed.
The key is not to track every number available. It is to focus on the figures that connect daily operations with revenue, costs and profitability.
Why Daily Financial Tracking Matters in Hotel Management
Hotel performance can change quickly because room inventory is perishable. A room that remains unsold tonight cannot be sold tomorrow to recover today’s lost revenue.
Daily reporting also helps managers identify problems before they become month-end surprises. A sudden fall in occupancy, higher labour costs, weaker direct bookings or rising distribution costs can all affect profitability even when headline revenue appears healthy.
The goal is therefore not simply to collect numbers. It is to understand what changed, why it changed and whether the hotel needs to respond.
For a broader introduction to the subject, see this guide to hotel finance.
1. Occupancy
Occupancy shows how much of the hotel’s available room inventory has been sold for a particular period. It is generally calculated by dividing occupied rooms by available rooms.
For example, if a hotel has 100 available rooms and sells 75, occupancy is 75%.
Occupancy is useful, but it should not be viewed in isolation. Filling more rooms does not necessarily mean the hotel is generating more profit. A property can increase occupancy by reducing room rates or accepting bookings through higher-cost distribution channels.
Daily occupancy should therefore be considered alongside ADR and RevPAR.
2. Average Daily Rate (ADR)
ADR measures the average room rate achieved for occupied rooms. It is calculated by dividing room revenue by the number of rooms sold.
A hotel might have strong occupancy but weak ADR, or lower occupancy with a much stronger rate. Looking at ADR alongside occupancy gives managers a clearer picture of the hotel’s room revenue performance.
Rate changes should also be considered in context. A higher ADR may reflect stronger demand, a different room mix or a change in promotional activity rather than simply a better pricing decision.
3. RevPAR
Revenue per Available Room, or RevPAR, brings occupancy and room rate together. It is calculated by dividing room revenue by available rooms. It can also be derived by multiplying occupancy by ADR when the figures use compatible periods and definitions.
RevPAR is particularly useful because it considers both how many rooms were sold and the rate achieved for those rooms. A hotel with a high ADR but many empty rooms may produce less room revenue than expected, while a hotel with high occupancy at heavily discounted rates can face a similar problem.
What Is RevPAR and How to Improve It provides further context on this metric.
4. Room Revenue and Total Hotel Revenue
Managers should know how much revenue the hotel is generating and where that revenue is coming from.
Room revenue is only one part of the picture. Depending on the property, revenue may also come from food and beverage, meetings and events, parking, spa services, retail, activities and other departments. Reviewing these streams separately can reveal changes that are hidden when everything is combined into one total.
Hospitality Revenue Streams explains the different sources of hospitality revenue in more detail.
For properties with several revenue-generating departments, Total Revenue per Available Room (TRevPAR) can provide another useful measure. Unlike RevPAR, TRevPAR considers total hotel revenue rather than room revenue alone.
5. Labour Cost
Labour is one of the major operating costs in many hotels, so managers should keep a close eye on payroll relative to revenue.
A daily labour-cost review can help identify situations such as excessive staffing during a quiet period, overtime, unexpected roster changes or labour costs increasing faster than revenue.
The useful question is not simply “How much have we spent on wages?” It is whether staffing levels and labour costs are appropriate for the hotel’s current level of business.
6. Departmental Revenue and Costs
A hotel can look healthy at the top-line level while one department is underperforming.
For example, restaurant sales may be strong but food costs may also have increased. A function may generate substantial revenue while additional labour, supplies and other costs reduce its contribution.
Monitoring departmental revenue and major costs helps managers understand where the hotel’s operating result is actually being generated. This is also where consistent financial reporting becomes important. The 12th Revised Edition of the Uniform System of Accounts for the Lodging Industry was adopted from 1 January 2026 and provides an updated framework for lodging financial and operating reporting.
7. Gross Operating Profit and GOPPAR
Revenue alone does not tell a hotel manager whether the property is making money from its operations.
Gross Operating Profit (GOP) helps show the operating result after relevant operating expenses. GOPPAR, or Gross Operating Profit per Available Room, takes that concept further by relating operating profit to available room inventory.
This can be more useful than looking at occupancy or ADR alone because it brings profitability into the analysis. Industry hotel performance reporting commonly uses GOPPAR alongside measures such as RevPAR, TRevPAR and labour costs.
8. Cost Per Occupied Room
Cost Per Occupied Room (CPOR) can help managers understand the operating cost associated with rooms that are actually occupied.
The exact costs included can vary depending on the hotel’s reporting approach, so the important point is to use a consistent definition. Tracking the measure over time can help identify whether room-related costs are rising faster than room revenue.
This becomes particularly useful when comparing periods with different occupancy levels.
9. Distribution and OTA Costs
A booking is not equally valuable simply because it generates the same room rate.
Online travel agencies and other distribution channels can involve commissions or other acquisition costs. A hotel receiving a $200 booking through one channel may retain a different amount from a $200 booking generated through another channel.
Managers should therefore consider channel mix and distribution costs when reviewing daily revenue. This gives a clearer picture of the revenue the hotel actually retains.
10. Cash Position and Receivables
Profit and cash are not the same thing.
Managers responsible for hotel financial performance should understand the property’s current cash position and be aware of significant amounts still owed to the hotel. This can be particularly relevant where corporate accounts, events, groups or other arrangements involve payment after the service has been provided.
Cash and receivables do not necessarily need to be analysed in the same way as occupancy or ADR every morning, but they should form part of the hotel’s regular financial control process.
11. Actual Results Against Budget and Forecast
A daily figure becomes much more meaningful when there is something to compare it with.
A hotel manager might compare today’s occupancy with the expected level, room revenue with forecast, or labour costs with the budgeted position. Looking at the variance can reveal issues that a standalone number would not show.
For example, $30,000 in room revenue may sound positive. If the hotel expected $40,000 based on demand and available inventory, the same figure tells a very different story.
Daily reporting should therefore focus on actual performance, expected performance and the reason for the difference.
Which Metrics Should a Hotel Manager Prioritise?
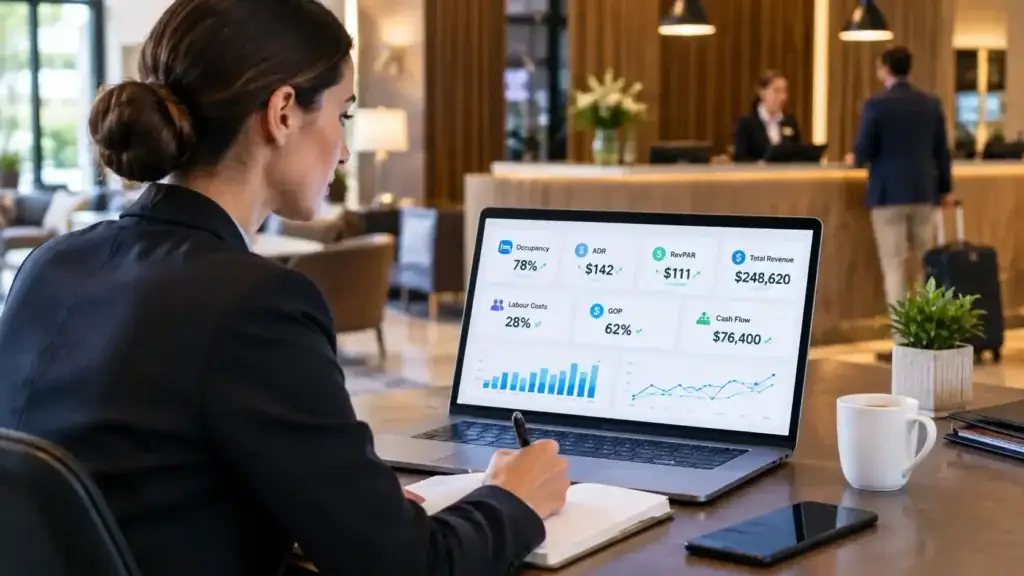
Not every hotel needs the same dashboard. A practical daily review will usually start with occupancy, ADR, RevPAR, room revenue and total revenue. Managers should then look at labour costs, key departmental costs, distribution costs and the operating profit position where those figures are available.
The most useful dashboard is one that connects these numbers rather than displaying them as isolated statistics.
For example:
Occupancy → ADR → RevPAR → Revenue → Costs → Operating Profit
This sequence helps explain what happened rather than simply reporting what happened.
A hotel that sees occupancy fall should investigate demand and booking pace. If occupancy is strong but RevPAR is weak, rate may need attention. If revenue is growing but profit is not, the focus should move towards labour, departmental costs, distribution expenses or other operating costs.
Daily Metrics Should Lead to Decisions
The purpose of financial reporting is not to create a longer spreadsheet. It is to help managers make better operational decisions.
If labour costs are rising while occupancy is falling, staffing levels may need review. If occupancy is increasing but ADR is declining, managers may need to examine pricing and promotions. If revenue is healthy but GOP is weakening, the problem is likely further down the income statement.
This is why the relationship between metrics matters more than any single number.
Hotel managers can also use historical performance, current booking information and forecasts to put today’s results into context. Data-driven forecasting can be useful when turning operational data into forward-looking decisions.
How Often Should Hotel Financial Metrics Be Reviewed?
Daily review is most useful for fast-moving operational metrics such as occupancy, ADR, RevPAR, room revenue, bookings and labour deployment.
Other financial figures may be more reliable when reviewed over a longer period. Final accounting results, departmental profitability, accruals and some cost measures can change as transactions are posted and reconciled.
This distinction matters. A daily dashboard should be treated as a management tool, not automatically as the final accounting record.
A sensible process is to review the daily operating picture each morning, investigate significant variances during the day and use regular financial reporting to confirm the underlying results.
Building a Practical Hotel Finance Dashboard
A useful dashboard does not need dozens of metrics. It should give the manager a quick view of demand, rate, revenue, costs and profitability.
A simple daily view could include:
| Area | Metric | What it helps explain |
| Demand | Occupancy | How much room inventory is being sold |
| Rate | ADR | Average rate achieved |
| Room performance | RevPAR | Room revenue performance across available inventory |
| Revenue | Room and total revenue | How much the hotel is generating |
| Costs | Labour and key departmental costs | Where operating expenses are moving |
| Distribution | Channel or OTA costs | How much revenue is retained after acquisition costs |
| Profitability | GOP / GOPPAR | Operating financial performance |
| Cash | Cash and receivables | Short-term financial position |
| Planning | Budget / forecast variance | Whether performance is tracking expectations |
The exact dashboard should reflect the hotel’s size, business model, departments and reporting systems. What matters most is consistency and the ability to investigate significant changes quickly.
Final Takeaway
Hotel managers do not need to watch every financial figure every day. They need a focused set of metrics that explains what is happening to demand, room rates, revenue, costs and profitability.
Occupancy, ADR and RevPAR provide the foundation for understanding room performance. Revenue by department shows where money is being generated, while labour, distribution and operating costs explain what the hotel is retaining. GOP and GOPPAR then help connect operating performance with profitability.
When these figures are reviewed together and compared with budget, forecast and previous performance, daily financial reporting becomes much more useful than a simple list of numbers.
Hotels that need stronger financial reporting processes can also explore Accounting and Financial Support for Hospitality or learn more about hotel finance management.